Market overview — definition, scope, and industry significance of Bolts Market
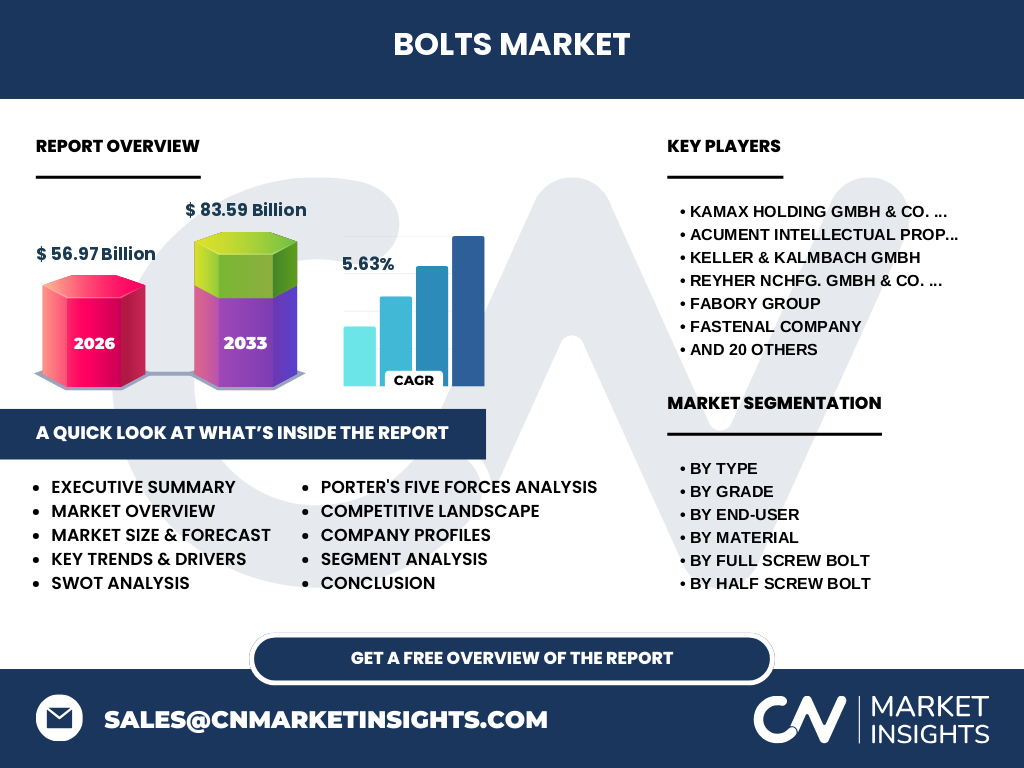
Our analysis indicates that the Bolts Market encompasses the manufacture and distribution of threaded fasteners essential for structural integrity across heavy industries. Valued at 56.97 Billion in 2026, this sector underpins global mechanical assembly, requiring rigorous compliance with ISO and ASTM metallurgy standards.
Key market drivers, restraints, challenges, and opportunities shaping Bolts Market
The market is propelled by rapid urbanization and infrastructure investments, though tempered by raw material price volatility in carbon and alloy steels. Supply chain bottlenecks at major maritime hubs present ongoing logistical hurdles, creating lucrative opportunities for regionalized sourcing and high-tensile innovations.
Emerging trends and growth patterns in Bolts Market
Industry trends highlight a decisive shift toward corrosion-resistant coatings and lightweight plastic variants for electric vehicle architectures. Smart fastening technologies embedded with IoT sensors are gaining traction, allowing operators to monitor real-time preload degradation in critical infrastructure.
COVID-19 impact analysis — how the pandemic affected Bolts Market and the recovery trajectory
The pandemic severely disrupted the Bolts Market through factory shutdowns and raw material shortages of nickel and chromium. Recovery has been accelerated by automated manufacturing lines and localized inventory buffers implemented by major distributors to mitigate future geopolitical or biological shocks.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is moderately fragmented, featuring global giants alongside specialized precision manufacturers. Firms like Fastenal Company and Würth Industrie Service leverage massive vendor-managed inventory networks, while technical specialists focus on aerospace-grade alloy configurations.
Executive summary — high-level synthesis of key findings about Bolts Market
Our comprehensive review shows the Bolts Market poised for robust expansion, driven by aerospace resurgence and green energy infrastructure. Key strategic imperatives include supply chain resilience, adoption of Grade 10.9 and 12.9 fasteners, and localized distribution hubs to counter escalating logistics costs.
Market forecast — projected growth from 2027 to 2033
Based on our research, the Bolts Market is projected to reach 83.59 Billion by 2033, expanding at a steady CAGR of 5.63% from 2027. This growth trajectory reflects sustained demand for high-strength structural assemblies in wind turbine towers and high-speed rail networks.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market divides into categories including Half Screw Bolt and Full Screw Bolt designs, material types spanning metal and plastic, and performance grades ranging from Grade 5.8 to 12.9. These tiers dictate load-bearing capacities for automotive, aerospace, and construction end-users.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily weighted toward industrialized zones with dense automotive and machinery manufacturing clusters. Asia-Pacific dominates volume consumption due to rapid industrialization, while North America and Europe prioritize high-specification aerospace and wind-energy fasteners.
In-depth regional review — detailed examination of key regional markets
In North America, stringent OSHA regulations and infrastructure stimulus bills drive demand for domestic, high-grade structural fasteners. Meanwhile, European markets focus intensely on lightweight mobility and circular economy compliance, pushing suppliers toward recyclable alloy formulations and low-emission production.
Company profiles — strategic positioning of leading companies in Bolts Market
Industry leaders maintain distinct competitive moats. KAMAX Holding GmbH & Co. KG. specializes in lightweight automotive fasteners, whereas Dokka Fasteners AS anchors the heavy wind energy sector with proprietary high-tensile bolts. Fabory Group and Keller & Kalmbach GmbH excel in vendor-managed inventory solutions.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to specialized alloy requirements, while buyer power is high among automotive OEMs demanding cost-down pressures. The threat of substitutes is low in critical structural applications, though plastic variants challenge metal in lower-stress consumer goods.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths lie in established global distribution networks and advanced metallurgy; weaknesses include high vulnerability to steel price fluctuations. Opportunities abound in offshore wind energy and EV lightweighting, while threats stem from geopolitical trade tariffs and counterfeit low-grade imports.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw wire rod extraction and metallurgical alloying, flowing through cold-heading, thread-rolling, and surface-treatment facilities. Finished components are distributed via industrial wholesalers directly to automotive assembly lines, construction sites, and aerospace manufacturers.
Investment insights — strategic recommendations and high-potential areas
Investors should target manufacturers capable of producing Grade 12.9 and specialized socket bolts tailored for renewable energy installations. Strategic mergers focusing on regional logistics integration will yield superior returns as industrial buyers consolidate their supplier bases.
Conclusion and key takeaways
The Bolts Market represents a vital, expanding segment driven by technological advancement and global infrastructure renewal. Stakeholders must embrace material science innovations and resilient supply chain strategies to capture the projected market valuation.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-level fastener executives, and secondary macroeconomic indicators across automotive and construction sectors to ensure high analytical fidelity.
Scope of the report — coverage parameters and limitations
This report covers global revenue and volume projections from 2027 to 2033, segmented by type, grade, material, and end-user. Limitations include unforeseen macroeconomic policy shifts and sudden regulatory changes regarding raw material export quotas.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves feature major investments in automated cold-forming machinery and eco-friendly zinc-flake coating lines by key players. Partnerships between fastener producers and EV startups aim to co-develop ultra-lightweight titanium and composite hybrid bolts.